From Geological Potential to Investment Readiness
Investment readiness begins long before an investor presentation is written. A mining project must be able to explain how its geological potential can become a viable business, what evidence supports that explanation and what the next commitment of capital will achieve.
The credibility of the proposition depends on the strength of those connections.
For project owners and boards, readiness is therefore an enterprise responsibility. Technical work, ownership, commercial assumptions, governance and management capability need to support the same story. Investors must be able to see both the opportunity and the uncertainty that still surrounds it.
An investor-ready project can explain its limitations without losing coherence. It knows which technical conclusions are independently supported, which commercial assumptions need testing and which management capabilities must still be recruited. That candour helps match capital to the actual stage of development. It also prevents a project from accepting an investment structure designed for a level of certainty that the business has not yet reached.
The Challenge
Mining projects necessarily develop through uncertainty. Problems arise when that uncertainty disappears from the presentation while remaining embedded in the business.
Untested recovery assumptions, incomplete infrastructure costs or an optimistic construction timetable can produce an attractive model without establishing a dependable investment case.
Ownership complications, undisclosed obligations and management gaps can have equally serious consequences. A funding request becomes difficult to assess when it does not explain what the money will accomplish or who will control its deployment. Capital may arrive before the organisation has the capability to use it responsibly, transferring unresolved problems into a more expensive stage of development.
A common difficulty is that different workstreams mature at different speeds. Geological information may be advanced while the ownership record remains incomplete. A financial model may be detailed while supplier quotations are preliminary. A project can therefore look substantially developed through one lens and remain immature through another. The material constraint is the least resolved dependency capable of undermining the next decision, not an average score across an attractive set of documents.
Pressure to raise capital can make this unevenness harder to discuss. Advisers refine the narrative, owners defend their valuation and prospective investors ask for stronger assurances. The response should be a clearer account of the evidence and the work required, rather than more confident language. Otherwise, the company risks making promises that later become sources of dispute, repricing or distrust when duediligence tests them.
Our Approach
Adecore treats readiness as a structured judgement about the next responsible action. We map what is known, inferred, assumed and unresolved, then connect technical and commercial evidence to the operating model, funding requirement and governance arrangements.
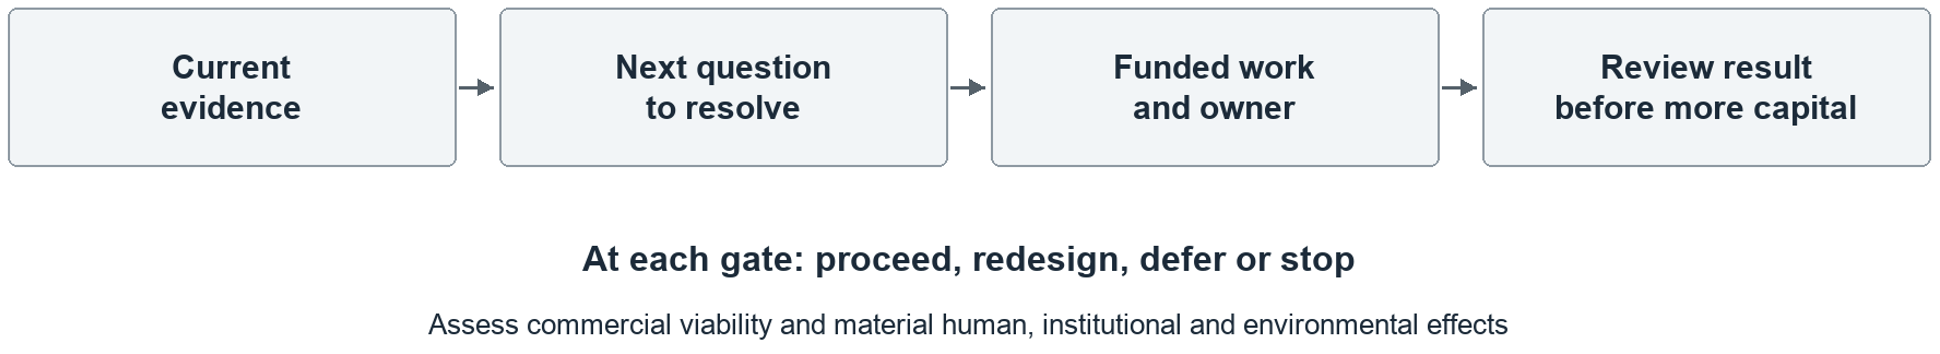
The assessment should make clear whether material gaps need to be closed, capital discussions can proceed, or oversight must be strengthened after funding.
The Adecore Intelligence Standard also requires attention to the consequences of the investment. Intended human, economic, institutional and environmental outcomes should inform the use of funds and the milestones against which progress is reviewed. By making evidence visible, assigning responsibility and building the client's ability to govern delivery, intelligence becomes a practical means of improving what capital achieves.
A useful readiness review produces an evidence register connected to the proposed investment decision. Each material claim should identify its source, date, limitations and relevance. The register should distinguish a management estimate from an external assessment and an indicative quotation from a committed price. This allows reviewers to focus their effort on the assumptions that matter most instead of treating every uploaded document as equally probative.
The level of evidence should increase as capital commitments become larger and harder to reverse. Early exploration may justify funding to answer a geological question. Development finance requires a much broader account of how the asset will be built and operated. The distinction matters because each funding stage should be supported by evidence appropriate to the decision being requested.
Geology must connect to recovery, processing, infrastructure, logistics and a credible market for the output. Financial assumptions should explain those relationships clearly enough to be challenged. Commodity prices, capital costs, operating costs, schedule and ramp-up need to be examined under different scenarios, so decision-makers can see which changes the project can absorb and which would undermine it.
The review should also produce an executable programme for closing gaps. Work needs an owner, a cost, a completion criterion and a relationship to the financing timetable. Some findings can be resolved through additional analysis; others require a different partner, project design or capital structure. Readiness improves when the organisation addresses the substance of the finding, rather than simply adding an explanation to the presentation.
Adecore Insight
Ownership and governance form part of that commercial assessment.
Licence and corporate ownership, beneficial interests, royalties, liabilities, shareholder rights and partner agreements influence both value and control. Investors need to understand the obligations they are inheriting and the decisions they will be able to influence. These arrangements should be established before funding makes ambiguity harder to resolve.
A credible use of funds explains how much capital is needed, why it is needed and the milestones it will deliver. It also identifies who authorises expenditure, how progress is reported and what happens if a milestone is missed. Management must demonstrate the ability to oversee technical work, contractors, regulatory obligations and stakeholder relationships, or present a credible plan for securing that capability.
Readiness should also make the project's wider consequences assessable. Worker capability and safety, local economic participation, transparent reporting and environmental responsibilities need appropriate resources and accountable owners. These are practical applications of Adecore's four Dimensions of Ethical Impact, to be revisited as evidence develops. The final decision may be to proceed, redesign the proposition or defer a commitment. What matters is that the decision follows from an honest assessment of the opportunity and that the organisation can sustain the discipline after the capital has been raised.
Funding structures should fit the project's uncertainty and cash generation. The analysis should examine the obligations attached to capital, including timing, control and any conditions that could become difficult during a delay. A project whose future cash receipts remain uncertain needs particular care before accepting fixed obligations based on an optimistic schedule. The right question is whether the proposed financing remains workable under credible downside conditions, with specialist advice on the actual terms.
Management reporting should be established before the investment closes. Investors and operators need a common understanding of milestone completion, budget variance and emerging risk. A study being commissioned is different from a study being completed, and completion is different from a result that supports proceeding. Reporting should preserve these distinctions so progress is measured by the evidence created rather than the activity undertaken.
The organisation should rehearse an adverse result. If further work weakens the resource case or raises expected costs, who can recommend stopping, and who decides? A programme that only rewards progress towards development can discourage unwelcome findings. Good governance makes room for a disciplined pause. Capital used to establish that a project should be redesigned or deferred may have protected far more value than capital used to maintain an increasingly unsupported timetable.
For the board, the final readiness question is practical: could a new decision-maker reconstruct why this commitment was made?If the answer depends on undocumented conversations or confidence in one individual, the institution remains fragile. A clear record of evidence, alternatives and responsibilities strengthens both the investment proposition and the organisation that must deliver it.