From Daily Fare Collections to Financeable Transport Businesses
A transport operator can carry passengers every day and still struggle to demonstrate the strength of the business to a financier.
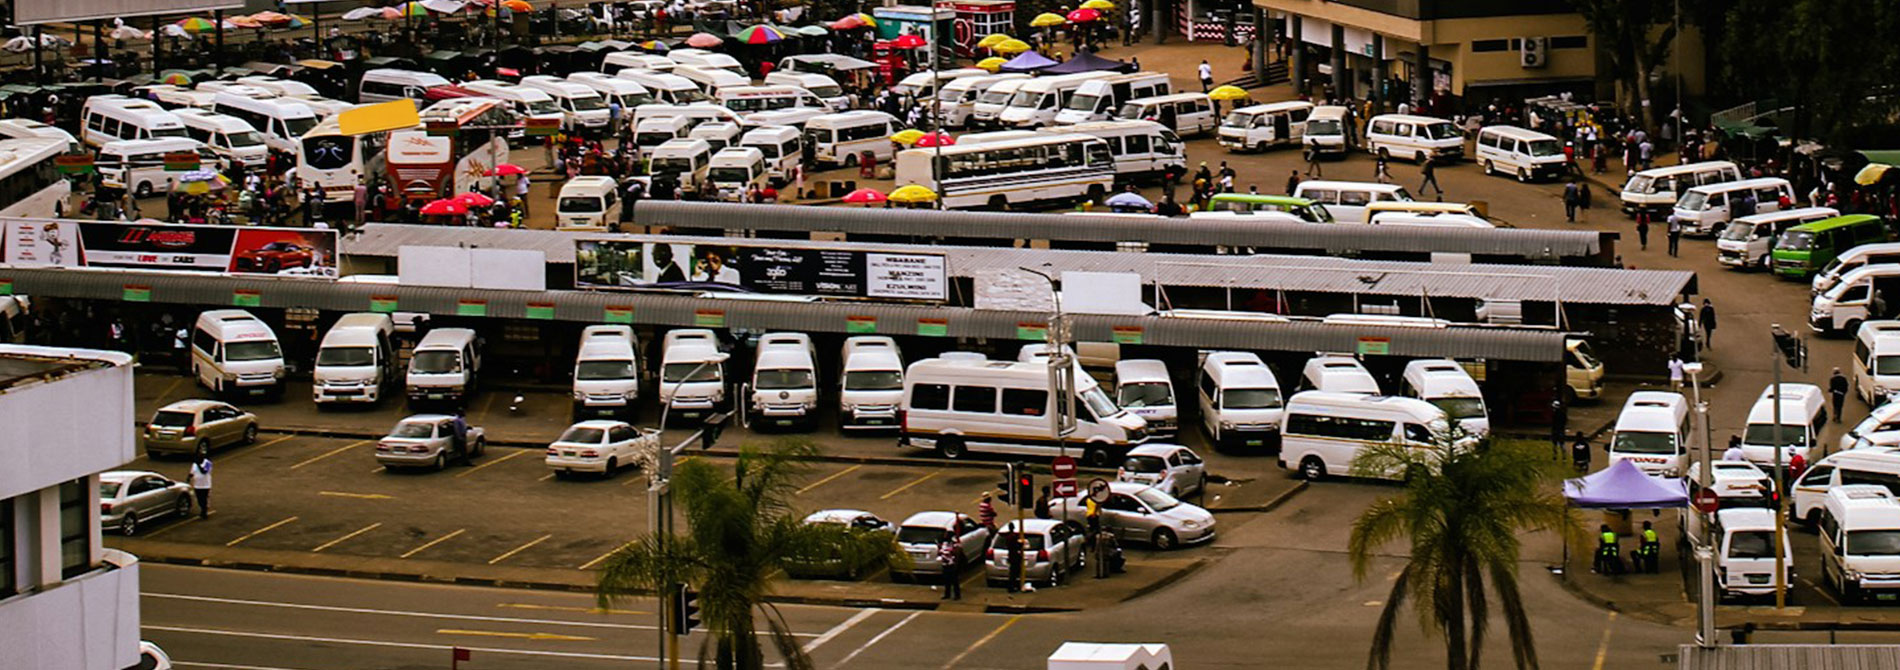
The activity is visible on the road, but the evidence needed to assess revenue, costs and repayment capacity may be fragmented. Money passes through different hands, maintenance is paid irregularly and vehicle performance is remembered more often than recorded. A productive enterprise can consequently appear less understandable than its daily operation suggests.
Digital fare collection creates an opportunity to improve that understanding. It can provide a more consistent record of transactions and, when connected with operating information, reveal how income relates to the service delivered. Yet a payment history is only one part of a financing case. The important question is whether the evidence can explain a sustainable business and support obligations the operator can reasonably meet, including during periods when the vehicle or route underperforms.
The Challenge
Revenue can be mistaken for repayment capacity. An operator may record substantial collections while facing high fuel costs, deferred maintenance or irregular payments to vehicle owners.
Revenue can be mistaken for repayment capacity. An operator may record substantial collections while facing high fuel costs, deferred maintenance or irregular payments to vehicle owners. A financier looking only at incoming transactions may miss the expenditure required to sustain the service. The resulting loan can appear affordable until a major repair or seasonal decline exposes the gap. Better data should reduce that misunderstanding rather than give incomplete analysis a more precise appearance.
The identity of the borrower also matters.The vehicle owner, route association, operating company and driver may each control different parts of the business. The party receiving fares may not own the asset, while the party responsible for repayments may not control dispatch or maintenance. A financing structure that ignores these relationships canplace obligations on someone who lacks the authority to manage the risks affecting repayment. Commercial responsibility needs to follow actual control.
Data quality introduces another difficulty.Transactions may be incomplete because some passengers pay cash, a device is offline or a vehicle moves between routes. A short period of unusually strong demand may be unrepresentative. Records can also reflect collection rules rather than the full economics of a journey. The lender and operator need to understand these limitations before treating a digital history as a stable forecast of future cash generation.
Access to finance can become harmful if it is designed around automatic deductions without adequate attention to operating needs. A repayment mechanism that captures revenue before essential expenses are met may protect collections briefly while weakening the service that generates them. The structure needs to consider continuity, affordability and the response to genuine disruption. Financial inclusion should be measured by whether an enterprise becomes more capable, not simply whether it receives a loan.
Our Approach
Adecore connects the payment record to the operating model.
Adecore connects the payment record to the operating model. The assessment asks which vehicles produced the revenue, what service they delivered and what it cost to keep them operating. It examines ownership, permits, contractual relationships and decision authority alongside financial information. The objective is to make the business understandable enough for appropriate financiers to assess it, while making uncertainty explicit. Technology supplies evidence; it does not replace credit judgement.
A practical model should distinguish ordinary operating expenditure, periodic maintenance, asset replacement and financing obligations. It should show how these demands interact over time. A vehicle can generate positive daily cash while accumulating an unfunded maintenance requirement. Recognising that obligation changes the apparent surplus and the financing discussion. It also encourages a more responsible view of asset care, linking financial discipline with passenger safety and service reliability.
Where records are weak, readiness may require a period of improved reporting before a funding proposal is appropriate. This is a productive outcome if it helps the operator establish credible costs, demonstrate stable practices and identify avoidable losses. The work should be proportionate to the enterprise and usable by its management. A complex model maintained only by an external adviser creates less lasting value than a simpler process the operator can apply consistently.
Evidence should also establish whether the proposed borrower has authority to enter the financing and direct the relevant cash flows. Where a route association coordinates vehicles owned by separate individuals, the financing assessment cannot simply treat all recorded revenue as one borrower's unrestricted income. The commercial relationships need to support the proposed obligation. Clarifying this structure can reveal a more appropriate borrower or transaction design, and it protects participants from commitments whose practical consequences they have not understood.
The intended impact is broader than approval of finance. More dependable maintenance, improved reporting and stronger cash planning can benefit the operator even if a proposed loan is deferred. Human impact includes the condition and reliability of the service.Economic impact includes sustainable investment rather than excessive debt.Institutional impact includes clear accountability for funds and assets.Environmental considerations become relevant where financing changes vehicle efficiency, maintenance practices or the use of the existing fleet.
Adecore Insight
Financing should be matched to the purpose of the expenditure.
Financing should be matched to the purpose of the expenditure. A short-lived cash requirement differs from a major overhaul or vehicle purchase. The analysis should explain when the benefit is expected, how long it will last and how repayment relates to the resulting cashflow. A mismatch between these periods can create pressure even when the underlying investment is sensible. Specialist financial advice should translate the operating case into appropriate terms.
Stress testing needs to reflect the business rather than rely on generic percentage reductions. What happens when a vehicle is unavailable for several weeks, a route is disrupted or a replacement part takes longer to arrive? The operator should know which costs continue and what alternatives are realistically available. The financier should understand the same picture. A contingency based on uninterrupted revenue from an asset that is being repaired is not a contingency.
Operators should also understand the data relationship. Who can access their transaction history, how can errors be corrected and what information moves with them if they change providers? These questions influence both trust and bargaining power. An operator should not discover that the evidence generated by years of activity is practically inaccessible when seeking another financial partner. Appropriate data governance can support participation without treating commercial information as an unrestricted resource.
A funding programme should review outcomes after disbursement. Did the financed repair improve availability? Did the new vehicle generate the expected service and cash? Were deductions affordable through normal fluctuations? The answers should improve future assessment and identify difficulties early. A programme that measures only lending volume or repayment collections may miss deterioration in service quality or dependence on increasingly expensive refinancing.
Vehicle replacement should be considered alongside the capability to maintain the asset. A loan may fund a better vehicle while leaving the operator without suitable technicians, parts accessor a reserve for downtime. The financing case should identify those requirements and their cost. This does not mean every financier must manage operations, but it does mean repayment analysis should recognise the conditions that sustain revenue. A well-structured investment links the asset, its support system and the service it is expected to deliver.
The opportunity is to make transport enterprises more legible without stripping away the context that makes them work. Verified records can help demonstrate value previously hidden by fragmented cash practices. Their strongest use is to support better decisions by operators and financiers together. Adecore's contribution is to connect that evidence with governance and operating capability, so access to capital becomes a means of strengthening the business rather than an additional pressure on it.